Updated September 14, 2026.
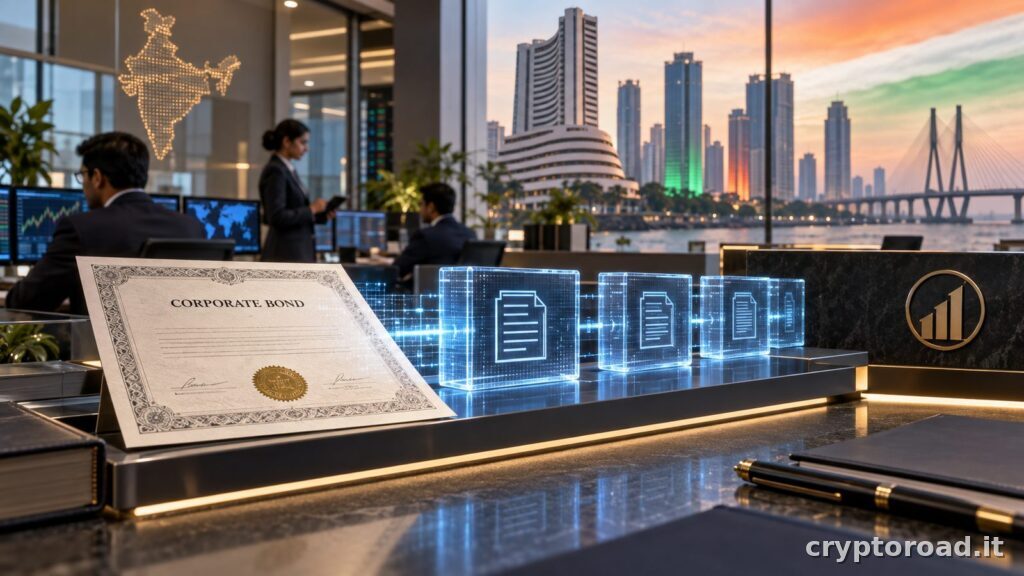
Demat 2.0 is India’s new pilot for tokenized corporate bonds, launched by the Securities and Exchange Board of India on September 10. The project brings distributed-ledger technology into a regulated perimeter without changing the bond’s legal nature or presenting it as a cryptocurrency.
India is not creating an unregulated parallel market. It is testing whether issuance, registration, transfer and reconciliation of traditional securities can become more efficient while preserving depositories, controls and investor rights.
| Item | Demat 2.0 |
|---|---|
| Authority | SEBI |
| Asset | Corporate bonds |
| Format | Tokenized record in a regulated pilot |
| Goal | Efficiency and traceability |
| Status | Experiment, not a general standard |
How Demat 2.0 works
In the conventional dematerialized system, ownership and transfers are recorded through depositories and securities accounts. Demat 2.0 tests a tokenized representation inside that architecture. The token should be understood as an operational record of an existing financial instrument, not an independent asset with separate value.
A shared and verifiable record could reduce manual reconciliation, errors and delays between issuance, deposit and settlement. The outcome still depends on integration with banks, investor identities, payments and procedures for correcting mistakes.
What changes in bond settlement
Tokenization can bring delivery of the security closer to payment and reduce the risk that one leg completes without the other. Genuine delivery-versus-payment still requires compatible money and legally clear transaction finality.
Our guide to bond prices and yields remains applicable: a tokenized register does not eliminate credit risk, duration, rate sensitivity or illiquidity. It changes how the instrument is administered, not the issuer’s economics.
Why the Indian pilot is not DeFi
Demat 2.0 operates under SEBI supervision and starts with identifiable corporate bonds. It does not promise permissionless access, anonymity or automatic global trading. Investors remain identified and intermediaries continue to have legal responsibilities.
This resembles the institutional model discussed in our guide to rights behind tokenized securities. Issuer, custody, legal register, redemption rights and jurisdiction matter more than the chosen blockchain.
Risks technology does not remove
Smart contracts and distributed ledgers add their own risks: bugs, compromised keys, node outages and disagreement between technical and legal records. A pilot must define who can correct a transaction, how inheritance or seizures work and which record controls a dispute.
Fragmentation is another risk. If every issuer chooses an incompatible network or standard, tokenization can create new islands instead of deeper liquidity. Interoperability and common rules may therefore matter more than theoretical ledger speed.
What to watch after launch
Useful evidence will include issuance volume, settlement time, operating costs and investor participation. It will also matter whether the pilot remains narrow or becomes a repeatable model for India’s corporate-bond market. Until SEBI publishes results, Demat 2.0 should be treated as experimental infrastructure.
Sources: SEBI Demat 2.0 FAQ; SEBI release, September 10, 2026.
How an issuance could work in the pilot
Under the proposed path, the issuer still follows corporate-bond rules while the security is represented within Demat 2.0. Depositories, intermediaries and investors must reconcile identity, ownership and transfers. The potential gain does not come from the token alone, but from reducing duplication between registry, custody and settlement systems.
The cash leg remains essential. If the bond moves on a ledger while payment settles through a separate process, counterparty risk does not disappear. A convincing pilot should demonstrate delivery versus payment, legal finality and procedures for mistakes, defaults or technical outages.
What tokenization does not change
Tokenization does not automatically improve the issuer’s credit quality or remove interest-rate and liquidity risk. A weak bond remains weak on a more efficient network. Investors still need to examine the prospectus, maturity, coupon, seniority, collateral and redemption terms.
The metrics that should decide Demat 2.0’s value
Beyond issuance volume, useful reporting should cover settlement failures, reconciliation time, cost per transaction, investor access and corporate-action handling. The decisive test will be whether the model expands from a controlled case to multiple issuers and intermediaries without creating fragmentation or another isolated technology silo.